
What are the 2 categories for all leases?
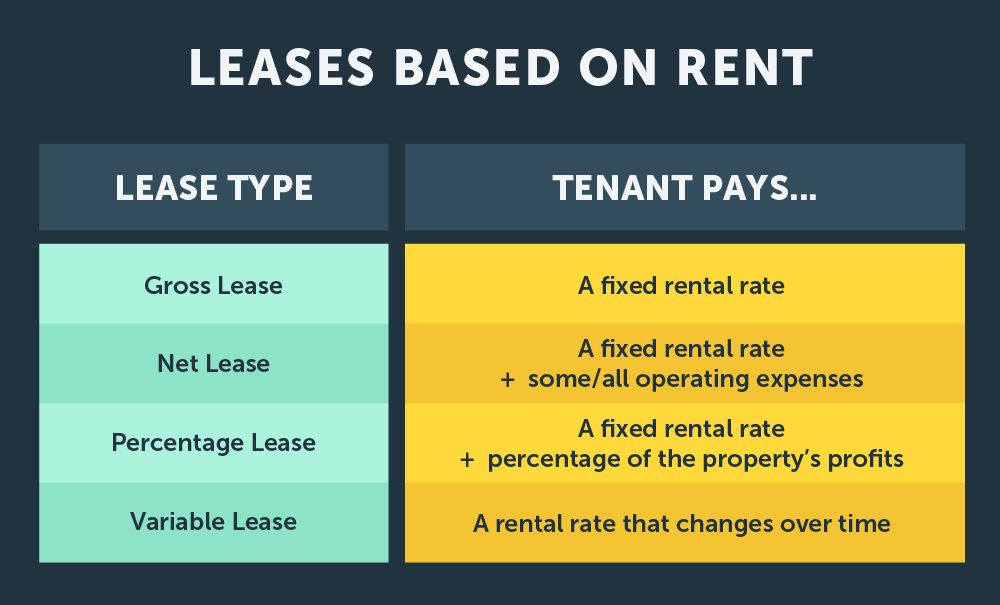
What are the 2 types of leases
The two most common types of leases are operating leases and financing leases (also called capital leases). In order to differentiate between the two, one must consider how fully the risks and rewards associated with ownership of the asset have been transferred to the lessee from the lessor.
What are the types of lease
Types of LeasingFinance Lease.Operating Lease.Leveraged Lease.Conveyance Lease.Sale and Leaseback.Complete and Non-Pay-Out Lease.Specialised Service Lease.Net and Non-Net Lease.
What are the two basic lease classifications by a lessor
There are two types of lease classifications for a lessee: finance and operating. There are three types of leases for a lessor: direct financing, sales-type, and operating leases.
What are the two types of leases compare and contrast
The two kinds of leases—capital leases and operating leases—each have different effects on business taxes and accounting. Capital leases transfer ownership to the lessee, while operating leases usually keep ownership with the lessor. Learn the details of both leasing options so you can make smart leasing decisions.
What are the most common forms of lease types
The three most common types of leases are gross leases, net leases, and modified gross leases.The Gross Lease. The gross lease tends to favor the tenant.The Net Lease. The net lease, however, tends to favor the landlord.The Modified Gross Lease.
What are the lease 3 forms
Lease terms generally come on 3 forms: fixed, periodic, and indefinite.
What is the classification of a lease normally
Classification of the lease is usually done at the starting of the contract or we can say that at the inception of the lease.
What are the classification of leases under IFRS
IAS 17 classifies leases into two types: a finance lease if the lease transfers substantially all the risks and rewards incidental to ownership; and. an operating lease if the lease does not transfer substantially all the risks and rewards incidental to ownership.
What are the two recognized lease accounting methods
There are two kinds of accounting methods for leases: operating and capital lease. A vast majority are operating leases. An operating lease is treated like renting — payments are considered operational expenses and the asset being leased stays off the balance sheet.
What are the four primary leases
There are, in general, four types of leases: the gross lease, the modified gross lease (or net lease), the triple net lease, and the bond lease.
What are the classifications of a lease by the lessee
Under FASB ASC 840, a lessee can classify a lease as either an Operating lease or a Capital lease.
What are the types of leases in IFRS 16
There are 2 types of leases defined in IFRS 16:A finance lease is a lease that transfers substantially all the risks and rewards incidental to ownership of an underlying asset.An operating lease is a lease other than a finance lease.
What are the two main types of accounting
There are two primary methods of accounting— cash method and accrual method. The alternative bookkeeping method is a modified accrual method, which is a combination of the two primary methods.
What is the IFRS standard for leases
Overview. IFRS 16 specifies how an IFRS reporter will recognise, measure, present and disclose leases. The standard provides a single lessee accounting model, requiring lessees to recognise assets and liabilities for all leases unless the lease term is 12 months or less or the underlying asset has a low value.
What are the 2 types of accounting year
What Are the Types of Accounting PeriodThe Calendar Year. Usually, the accounting period follows the Gregorian calendar year that consists of twelve months starting from January 1 to December 31.Fiscal Year. The fiscal year refers to an annual period that does not end on December 31.4–4–5 Calendar Year.
Does IFRS 16 apply to all leases
IFRS 16 introduces a single lessee accounting model and requires a lessee to recognise assets and liabilities for all leases with a term of more than 12 months, unless the underlying asset is of low value.
What are the 2 main types of accounting methods
There are two primary methods of accounting— cash method and accrual method. The alternative bookkeeping method is a modified accrual method, which is a combination of the two primary methods.
What are the 2 main parts of accounting
Key Takeaways
Two important types of accounting for businesses are managerial accounting and cost accounting. Managerial accounting helps management teams make business decisions, while cost accounting helps business owners decide how much a product should cost.
What are the classification of leases in IFRS 16
Classification of leases
There are 2 types of leases defined in IFRS 16: A finance lease is a lease that transfers substantially all the risks and rewards incidental to ownership of an underlying asset. An operating lease is a lease other than a finance lease.
What is lease classification under IFRS 16
IFRS 16 defines a lease term as the noncancellable period for which the lessee has the right to use an underlying asset including optional periods when an entity is reasonably certain to exercise an option to extend (or not to terminate) a lease.
What are two 2 objectives of accounting
Answer: The 2 objectives of accounting are – Maintaining a systematic record of all financial transactions and preparing financial reports to access the financial position of the business organisation.
What are the types of leases for lessee
The choices for a lessee are that a lease can be designated as either a finance lease or an operating lease. A lessee should classify a lease as a finance lease when any of the following criteria are met: Ownership of the underlying asset is shifted to the lessee by the end of the lease term.
What are 2 accounting principles
Some of the most fundamental accounting principles include the following: Accrual principle. Conservatism principle. Consistency principle.
What are the two 2 categories of accounting users
Users of accounting information are generally divided into two categories: internal and external.
What are the 2 accounts in accounting
Double-entry bookkeeping is a method of recording transactions where for every business transaction, an entry is recorded in at least two accounts as a debit or credit. In a double-entry system, the amounts recorded as debits must be equal to the amounts recorded as credits.


0 Comments